Home Loan EMI Guide 2026: Formula, Amortization Secrets & Prepayment Hacks to Save Lakhs | CalculatorLoop | Calculator Loop
financial
Verified Guide
Home Loan EMI Guide 2026: Formula, Amortization Secrets & Prepayment Hacks to Save Lakhs
Master EMI calculations with our complete guide. Learn reducing balance vs flat interest, amortize a ₹50 Lakh loan, and use 4 proven prepayment hacks to save ₹20+ Lakhs.
💼
CalculatorLoop Financial Expert Team
Financial Experts
Reviewed by Certified Financial Specialists
16 min read
Calculate This Instantly
Test your numbers directly with our free, real-time calculator.
Table of Contents
Home Loan EMI Guide 2026: The Complete Formula, Amortization Secrets & Prepayment Hacks to Save Lakhs
Whether you are purchasing your dream home, financing an automobile, or funding higher education, the three letters that dictate your monthly cash flow for the next 10 to 30 years are EMI (Equated Monthly Installment).
For the vast majority of borrowers, taking a loan is treated as a routine transactional event: you sign a loan agreement, agree to a monthly debit, and trust that the bank's schedule will eventually lead to complete ownership. However, beneath the surface of a simple fixed monthly payment lies a sophisticated amortization algorithm. If you do not understand how interest compounding, reducing balances, and amortization schedules work, you can easily end up paying more than double the original loan amount purely in cumulative interest.
In this comprehensive guide, our quantitative analysts and financial modeling specialists break down every layer of EMI mechanics. We provide the exact mathematical formula, dissect the amortization curve of a ₹50,00,000 home loan, explain why early prepayments generate exponential savings, and reveal four tactical prepayment strategies that can save you upwards of ₹20,00,000 to ₹30,00,000 in interest while shaving 7 to 10 years off your loan tenure.
1. What is an EMI? (Equated Monthly Installment Defined)
An Equated Monthly Installment (EMI) is an unequal blend of principal and interest calculated to produce an equal, predictable outflow of cash payable on a designated date each month over a pre-agreed tenure.
Every EMI payment serves two distinct functions simultaneously:
Interest Service: Compensating the lender for the capital risk and the time value of money based on the outstanding principal balance during that billing cycle.
Principal Liquidation: Reducing the underlying principal liability so that future interest accruals decrease progressively over time.
The CalculatorLoop Financial Expert Team brings together certified analysts, chartered financial modelers, and quantitative researchers to deliver transparent, institutional-grade calculation guides.
Put this knowledge to use with our free financial calculators
financial
Verified Guide
Home Loan EMI Guide 2026: Formula, Amortization Secrets & Prepayment Hacks to Save Lakhs
Master EMI calculations with our complete guide. Learn reducing balance vs flat interest, amortize a ₹50 Lakh loan, and use 4 proven prepayment hacks to save ₹20+ Lakhs.
💼
CalculatorLoop Financial Expert Team
Financial Experts
Reviewed by Certified Financial Specialists
16 min read
Calculate This Instantly
Test your numbers directly with our free, real-time calculator.
Table of Contents
Home Loan EMI Guide 2026: The Complete Formula, Amortization Secrets & Prepayment Hacks to Save Lakhs
Whether you are purchasing your dream home, financing an automobile, or funding higher education, the three letters that dictate your monthly cash flow for the next 10 to 30 years are EMI (Equated Monthly Installment).
For the vast majority of borrowers, taking a loan is treated as a routine transactional event: you sign a loan agreement, agree to a monthly debit, and trust that the bank's schedule will eventually lead to complete ownership. However, beneath the surface of a simple fixed monthly payment lies a sophisticated amortization algorithm. If you do not understand how interest compounding, reducing balances, and amortization schedules work, you can easily end up paying more than double the original loan amount purely in cumulative interest.
In this comprehensive guide, our quantitative analysts and financial modeling specialists break down every layer of EMI mechanics. We provide the exact mathematical formula, dissect the amortization curve of a ₹50,00,000 home loan, explain why early prepayments generate exponential savings, and reveal four tactical prepayment strategies that can save you upwards of ₹20,00,000 to ₹30,00,000 in interest while shaving 7 to 10 years off your loan tenure.
1. What is an EMI? (Equated Monthly Installment Defined)
An Equated Monthly Installment (EMI) is an unequal blend of principal and interest calculated to produce an equal, predictable outflow of cash payable on a designated date each month over a pre-agreed tenure.
Every EMI payment serves two distinct functions simultaneously:
Interest Service: Compensating the lender for the capital risk and the time value of money based on the outstanding principal balance during that billing cycle.
Principal Liquidation: Reducing the underlying principal liability so that future interest accruals decrease progressively over time.
The CalculatorLoop Financial Expert Team brings together certified analysts, chartered financial modelers, and quantitative researchers to deliver transparent, institutional-grade calculation guides.
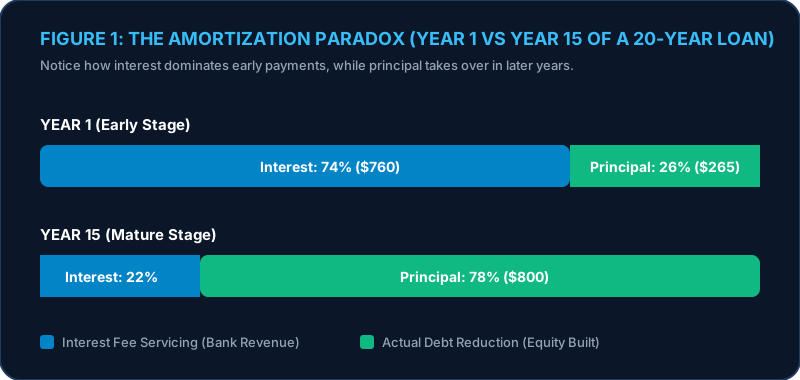
While your aggregate payment remains constant from Month 1 to Month 240 (on a fixed-rate 20-year facility), the internal ratio of your payment shifts dramatically across the life of the loan. In the first year, upwards of 75% to 85% of each monthly installment is swallowed directly by interest charges, leaving a minor fraction to reduce your loan principal. As the outstanding loan balance slowly declines, the monthly interest requirement falls, allowing an ever-increasing portion of your installment to attack the principal debt.
2. Reducing Balance Method vs. Flat Rate Interest: Avoid the Costliest Trap
When taking a loan—especially personal loans, used car loans, or dealer-financed appliances—borrowers frequently fall victim to the deceptive marketing of Flat Rate Interest versus Reducing Balance Interest.
The Flat Interest Rate Mirage
Under a flat rate calculation, interest is computed on the entire original principal for the entire loan tenure, completely ignoring the fact that you are steadily repaying the principal every single month!
Total Interest (Flat) = P × R × T
Monthly EMI (Flat) = frac{P + Total Interest}{T × 12}
Example: If you borrow ₹10,00,000 at a flat rate of 8% for 5 years:
Total Interest = ₹10,00,000 × 8% × 5 = ₹4,00,000
Total Repayment = ₹14,00,000
Monthly EMI = ₹14,00,000 / 60 = ₹23,333
The Reducing Balance Method (The True Standard)
In a reducing balance loan (standard for home loans and reputable bank financing), interest is calculated only on the outstanding balance remaining at the beginning of each billing month:
Interest for Month m = Outstanding Balance_{m-1} × (frac{Annual Rate}{12})
Under the reducing balance method at 8% per annum for ₹10,00,000 over 5 years:
Monthly EMI = ₹20,276
Total Interest Paid = ₹2,16,583
Total Repayment = ₹12,16,583
Comparison Parameter
Flat Rate Loan (8%)
Reducing Balance Loan (8%)
The Difference / Penalty
Principal Amount
₹10,00,000
₹10,00,000
₹0
Nominal Rate
8.00%
8.00%
Looks identical on paper
Effective APR
~14.65%
8.00%
Flat rate is nearly double!
Monthly Installment
₹23,333
₹20,276
₹3,057 higher per month
Total Interest Paid
₹4,00,000
₹2,16,583
₹1,83,417 extra wasted
[!WARNING]
Never sign a loan agreement quoting a "flat interest rate" without converting it to its Effective Annualized Percentage Rate (APR). An 8% flat rate is equivalent to approximately 14.5% to 15% reducing rate. Always demand the reducing balance schedule.
3. The Mathematical Formula Behind EMI
The standard mathematical formula utilized by financial institutions worldwide, banking algorithms, and CalculatorLoop's EMI Calculator is derived from the Present Value of an Ordinary Annuity:
E = (P · r · (1 + r)ⁿ / (1 + r)ⁿ - 1)
Where:
E = Equated Monthly Installment (EMI) payable each month
P = Principal loan amount sanctioned and disbursed
r = Periodic monthly interest rate, computed as: frac{Annual Interest Rate (in %)}{12 × 100}
n = Total repayment duration expressed in integer months (e.g., 20 years = 240 months)
Step-by-Step Manual Calculation Walkthrough
Let us solve this step-by-step for a realistic scenario:
Your monthly EMI is precisely ₹24,624. Over 180 months, total repayments equal ₹44,32,320, consisting of ₹25,00,000 in principal recovery and ₹19,32,320 in net interest payments.
4. Case Study: ₹50 Lakh Home Loan Amortization Breakdown
Figure 1: The Amortization Paradox - Interest vs Principal Shift
To understand how interest eating away at your wealth actually operates in real life, consider the benchmark Indian urban home loan:
Principal (P): ₹50,00,000
Interest Rate (R): 8.75% per annum (floating)
Tenure (n): 20 Years (240 Months)
Monthly EMI: ₹44,186
Total Amount Repaid: ₹1,06,04,524 (Over ₹1.06 Crore!)
Total Interest Burden: ₹56,04,524 (You pay 112% of the loan in interest alone!)
Detailed Year-by-Year Amortization Schedule Table
Year
Annual EMI Paid
Principal Repaid
Interest Repaid
Outstanding Balance at Year End
% of EMI Going to Interest
Year 1
₹5,30,227
₹95,959
₹4,34,268
₹49,04,041
81.9%
Year 2
₹5,30,227
₹1,04,705
₹4,25,522
₹47,99,336
80.3%
Year 3
₹5,30,227
₹1,14,250
₹4,15,977
₹46,85,086
78.5%
Year 4
₹5,30,227
₹1,24,665
₹4,05,562
₹45,60,421
76.5%
Year 5
₹5,30,227
₹1,36,031
₹3,94,196
₹44,24,390
74.3%
Year 7
₹5,30,227
₹1,62,187
₹3,68,040
₹41,12,652
69.4%
Year 10
₹5,30,227
₹2,11,466
₹3,18,761
₹35,27,991
60.1%
Year 13
₹5,30,227
₹2,75,721
₹2,54,506
₹27,65,716
48.0%
Year 15
₹5,30,227
₹3,28,742
₹2,01,485
₹21,37,185
38.0%
Year 18
₹5,30,227
₹4,28,633
₹1,01,594
₹9,93,923
19.2%
Year 20
₹5,30,227
₹5,07,678
₹22,549
₹0
4.3%
Critical Takeaways from the Amortization Data:
The 5-Year Milestone Shock: After 5 full years of religiously paying ₹44,186 every single month (totaling ₹26,51,135 out of pocket), your outstanding principal has only dropped from ₹50 Lakh to ₹44.24 Lakh! Over ₹20.7 Lakhs went straight into the bank's profit ledger.
The Crossover Point: It takes almost 12 to 13 years before more than 50% of your monthly EMI is applied toward principal reduction rather than interest.
The Window of Opportunity: Any extra payment made in Years 1 through 7 has an astronomical compounding impact because it prevents dozens of future compound interest cycles.
5. The 4 Proven Prepayment Strategies (Save ₹15L to ₹30L in Interest)
Prepayment is the legal, mathematical cheat code of debt management. When you make a partial prepayment toward a floating-rate home loan in India, the RBI prohibits banks from charging any prepayment penalties. 100% of your prepayment is deducted directly from the principal loan balance.
Here are the four most powerful prepayment protocols modeled by our financial engineers:
Strategy 1: The "1 Extra EMI Per Year" Protocol
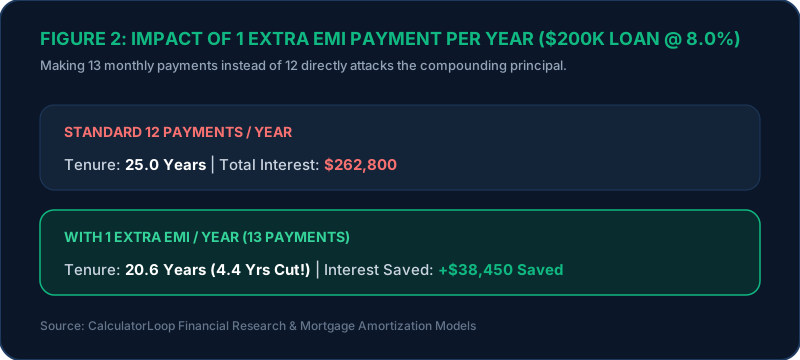
Figure 2: Impact of 1 Extra EMI Payment Per Year
Mechanism: Every year, make one additional EMI payment (13 payments instead of 12). You can time this with your annual company performance bonus, Diwali incentive, or tax refund.
The Numbers on a ₹50L, 20-Year Loan @ 8.75%:
Normal Tenure: 20 Years (240 Months) | Normal Interest: ₹56,04,524
With 1 Extra EMI/Year: Tenure drops from 20 Years to ~16 Years!
Total Interest Saved: ₹11,45,000+
Time Saved: 4 full years of debt freedom!
Strategy 2: The "5% Annual Step-Up EMI" Strategy
Mechanism: As your career progresses, your salary typically rises between 6% and 12% annually. By instructing your bank to increase your monthly EMI by just 5% once every 12 months:
Year 1 EMI: ₹44,186
Year 2 EMI: ₹46,395 (+₹2,209)
Year 3 EMI: ₹48,715 (+₹2,320)
Year 4 EMI: ₹51,151 (+₹2,436)
The Results:
Your 20-year loan is completely eradicated in just 12.5 Years!
Total Interest Saved: ₹22,80,000+ (Saving almost half the total interest!)
Strategy 3: Lump-Sum Prepayment at Strategic Milestones
Mechanism: Making a lump-sum principal repayment of ₹2,00,000 to ₹5,00,000 during the initial 36 months of the loan.
Why Early Timing Matters:
A ₹3,00,000 prepayment made at the end of Year 2 saves approximately ₹9,45,000 in future cumulative interest and cuts tenure by 28 months.
That same ₹3,00,000 prepayment made in Year 15 saves less than ₹1,15,000 in interest because most interest has already been extracted.
Strategy 4: Tenure Reduction vs. EMI Reduction (The Crucial Choice)
Whenever you make a partial prepayment, your bank will present you with two options:
Reduce the Loan Tenure (keep the monthly EMI constant).
Reduce the Monthly EMI (keep the remaining loan tenure constant).
[!IMPORTANT]
Always choose Tenure Reduction. Reducing your tenure keeps your amortization velocity high and maximizes mathematical compounding savings. Reducing your EMI gives immediate monthly budget relief, but results in 40% to 60% lower total interest savings over the life of the loan.
6. Fixed vs. Floating Interest Rates in 2026
When structuring your loan facility, understanding the underlying benchmark rate mechanism is paramount.
External Benchmark Lending Rate (EBLR / RLLR)
Since October 2019, the Reserve Bank of India mandated that all retail floating-rate loans from scheduled commercial banks must be linked to an external benchmark, overwhelmingly the RBI Repo Rate:
Home Loan Rate = RBI Repo Rate + Bank Spread (Margin) + Credit Risk Spread
If the RBI cuts the repo rate by 50 basis points (0.50%), banks are legally required to pass the reduction to borrowers within the reset window (usually within 3 months).
Conversely, when inflationary cycles cause rate hikes, your home loan tenure or EMI expands automatically.
Comparative Framework: Fixed vs. Floating
Feature
Floating Rate Home Loan
Fixed Rate Home Loan
Current Market Range
8.35% – 9.25%
9.80% – 11.50%
RBI Prepayment Penalty
0% (Zero penalty by law)
2% – 3% prepayment penalty often applies
Market Sensitivity
Adjusts automatically with RBI policy
Immune to rate hikes, but misses rate cuts
Suitability
Ideal for 95%+ of Indian home buyers
High-inflation risk aversion or short tenures
7. Tax Deductions on Home Loans in India: Section 24(b) & Section 80C
Smart borrowers leverage tax deductions under the Indian Income Tax Act to effectively slash their net borrowing cost:
1. Interest Deduction: Section 24(b)
Maximum Limit: Up to ₹2,00,000 per financial year on interest paid for a self-occupied property.
Let-out Property: If the property is rented out, the entire interest paid can be set off against rental income, subject to an overall loss cap of ₹2,00,000 across house property heads per year.
Tax Savings Impact: For an individual in the 30% tax bracket (+ cess), claiming the full ₹2,00,000 deduction saves ₹62,400 in direct income tax every year.
2. Principal Repayment: Section 80C
Maximum Limit: Up to ₹1,50,000 per financial year for the principal repayment component, along with stamp duty and registration charges paid in the year of purchase.
Lock-in Period: You cannot transfer or sell the property within 5 years of possession, or the claimed deductions are reversed and taxed as income.
Note: Section 80C is only available if you opt for the Old Tax Regime. Under the New Tax Regime, 80C deductions are not available, though Section 24(b) on let-out properties retains specific provisions.
3. Joint Home Loan Optimization (The Double Deduction Hack)
If you co-sign a home loan with your spouse, parent, or working sibling and both are co-owners of the property:
Both co-borrowers can independently claim up to ₹2,00,000 each under Section 24(b) (Total: ₹4,00,000/year).
Both can claim up to ₹1,50,000 each under Section 80C (Total: ₹3,00,000/year).
Combined annual tax shield = Up to ₹7,00,000 in deductions, saving over ₹2,18,000 in income tax annually!
8. Associated Hidden Costs: What Lenders Do Not Highlight
When budgeting for a loan, the principal and interest are not the only expenses. Always factor in:
Processing Fees: Typically 0.25% to 0.50% of the loan amount + 18% GST (often negotiable or waived during festive promotions).
MODT Charges (Memorandum of Deposit of Title Deeds): 0.1% to 0.5% of loan value depending on state government stamp rules.
Property Valuation & Legal Verification Fees: ₹5,00,000 to ₹15,000 per property dossier.
Loan Protection Insurance: Banks frequently pressure borrowers into single-premium credit protection insurance bundled into the loan. Always compare term life insurance quotes independently rather than buying expensive bundled policies.
9. The Golden Rules of Prudent Borrowing
To ensure your loan enhances your net worth rather than triggering financial distress, apply these institutional risk guidelines:
The 40% FOIR Rule: Your Fixed Obligation to Income Ratio (FOIR)—including your home loan EMI, car loans, and credit cards—should never exceed 40% to 45% of your net monthly take-home salary.
Maintain a 6-Month EMI Contingency Buffer: Keep 6 months of EMI payments in a liquid mutual fund or high-interest sweep account before taking possession, safeguarding you against job loss or medical emergencies.
Review Interest Rates Annually: Check your lender's current spread against competing PSU and private banks. If your rate is more than 0.50% higher than prevailing market rates for your credit tier, request an internal balance conversion (switch fee of ₹1,000–₹5,000) or initiate an external balance transfer.
10. Frequently Asked Questions (FAQ)
Q1. Can I reduce my home loan EMI if the RBI cuts interest rates?
Yes. Under the External Benchmark Lending Rate (EBLR) framework, banks must revise their benchmark floating rates in tandem with RBI repo rate cuts. By default, most lenders adjust your loan tenure downward while keeping your monthly EMI constant. You can explicitly request your bank branch or net banking portal to reduce the EMI instead if monthly cash flow relief is your primary objective.
Q2. Is there any prepayment penalty on home loans in India?
According to binding RBI guidelines, banks, housing finance companies (HFCs), and NBFCs cannot charge any prepayment penalty or foreclosure fee on floating-rate individual home loans, regardless of whether the prepayment is partial or full. However, if the loan is in the name of a business entity or has a fixed interest rate, prepayment charges may apply.
Q3. How does increasing my loan tenure affect my total interest?
Increasing your tenure reduces your monthly EMI, which makes initial loan qualification easier, but massively increases your total interest outflow. For example, taking a ₹40 Lakh loan at 9% for 30 years instead of 20 years reduces your EMI by only ₹5,000/month, but increases your total interest bill by a staggering ₹26,80,000!
Q4. Which is better: paying off a home loan early or investing in mutual funds via SIP?
This depends on your expected post-tax investment return versus your home loan interest rate:
If your home loan interest rate is 8.5% (effective post-tax cost ~6.5% after Section 24b deductions), and long-term equity SIPs historically return 12% to 14% CAGR, investing surplus funds in equity mutual funds generates greater mathematical wealth over 15 to 20 years.
However, for psychological peace of mind and guaranteed risk-free return on capital, eliminating debt early is unbeatable. A hybrid approach—paying 1 extra EMI per year while running a disciplined SIP alongside—delivers the ideal balance.
Q5. Can a high credit score really lower my home loan EMI?
Absolutely. Most major Indian lenders (State Bank of India, HDFC Bank, Bank of Baroda, ICICI) employ risk-based pricing matrices. A borrower with a CIBIL score of 780+ typically receives interest rates 0.40% to 0.75% lower than a borrower with a score of 680. On a ₹50 Lakh, 20-year loan, a 0.50% rate difference translates to savings of over ₹3,50,000 in interest.
Q6. What happens if I miss an EMI payment?
Missing an EMI triggers an immediate late payment penalty (usually 2% per month on the overdue amount), bounces penal charges (₹500+), and is reported to credit bureaus (CIBIL, Experian, Equifax), causing a sharp drop of 40 to 80 points in your credit score. If non-payment extends beyond 90 days, the loan is classified as a Non-Performing Asset (NPA), initiating proceedings under the SARFAESI Act.
Conclusion: Take Control of Your Loan Today
Your home loan does not have to be a 20-year financial burden. By understanding the underlying reducing balance mathematics, monitoring your amortization schedule, and executing structured prepayment protocols like the 1-extra-EMI or 5%-annual-step-up strategy, you can reclaim your financial freedom years ahead of schedule and save tens of lakhs in unnecessary interest.
Put these numbers to work for your own portfolio:
Calculate your exact monthly payments, inspect your customized month-by-month amortization schedule, and experiment with prepayment scenarios using our institutional-grade Personal Loan & Home Loan EMI Calculator.
7.
7. Tax Deductions on Home Loans in India: Section 24(b) & Section 80C
While your aggregate payment remains constant from Month 1 to Month 240 (on a fixed-rate 20-year facility), the internal ratio of your payment shifts dramatically across the life of the loan. In the first year, upwards of 75% to 85% of each monthly installment is swallowed directly by interest charges, leaving a minor fraction to reduce your loan principal. As the outstanding loan balance slowly declines, the monthly interest requirement falls, allowing an ever-increasing portion of your installment to attack the principal debt.
2. Reducing Balance Method vs. Flat Rate Interest: Avoid the Costliest Trap
When taking a loan—especially personal loans, used car loans, or dealer-financed appliances—borrowers frequently fall victim to the deceptive marketing of Flat Rate Interest versus Reducing Balance Interest.
The Flat Interest Rate Mirage
Under a flat rate calculation, interest is computed on the entire original principal for the entire loan tenure, completely ignoring the fact that you are steadily repaying the principal every single month!
Total Interest (Flat) = P × R × T
Monthly EMI (Flat) = frac{P + Total Interest}{T × 12}
Example: If you borrow ₹10,00,000 at a flat rate of 8% for 5 years:
Total Interest = ₹10,00,000 × 8% × 5 = ₹4,00,000
Total Repayment = ₹14,00,000
Monthly EMI = ₹14,00,000 / 60 = ₹23,333
The Reducing Balance Method (The True Standard)
In a reducing balance loan (standard for home loans and reputable bank financing), interest is calculated only on the outstanding balance remaining at the beginning of each billing month:
Interest for Month m = Outstanding Balance_{m-1} × (frac{Annual Rate}{12})
Under the reducing balance method at 8% per annum for ₹10,00,000 over 5 years:
Monthly EMI = ₹20,276
Total Interest Paid = ₹2,16,583
Total Repayment = ₹12,16,583
Comparison Parameter
Flat Rate Loan (8%)
Reducing Balance Loan (8%)
The Difference / Penalty
Principal Amount
₹10,00,000
₹10,00,000
₹0
Nominal Rate
8.00%
8.00%
Looks identical on paper
Effective APR
~14.65%
8.00%
Flat rate is nearly double!
Monthly Installment
₹23,333
₹20,276
₹3,057 higher per month
Total Interest Paid
₹4,00,000
₹2,16,583
₹1,83,417 extra wasted
[!WARNING]
Never sign a loan agreement quoting a "flat interest rate" without converting it to its Effective Annualized Percentage Rate (APR). An 8% flat rate is equivalent to approximately 14.5% to 15% reducing rate. Always demand the reducing balance schedule.
3. The Mathematical Formula Behind EMI
The standard mathematical formula utilized by financial institutions worldwide, banking algorithms, and CalculatorLoop's EMI Calculator is derived from the Present Value of an Ordinary Annuity:
E = (P · r · (1 + r)ⁿ / (1 + r)ⁿ - 1)
Where:
E = Equated Monthly Installment (EMI) payable each month
P = Principal loan amount sanctioned and disbursed
r = Periodic monthly interest rate, computed as: frac{Annual Interest Rate (in %)}{12 × 100}
n = Total repayment duration expressed in integer months (e.g., 20 years = 240 months)
Step-by-Step Manual Calculation Walkthrough
Let us solve this step-by-step for a realistic scenario:
Your monthly EMI is precisely ₹24,624. Over 180 months, total repayments equal ₹44,32,320, consisting of ₹25,00,000 in principal recovery and ₹19,32,320 in net interest payments.
4. Case Study: ₹50 Lakh Home Loan Amortization Breakdown
Figure 1: The Amortization Paradox - Interest vs Principal Shift
To understand how interest eating away at your wealth actually operates in real life, consider the benchmark Indian urban home loan:
Principal (P): ₹50,00,000
Interest Rate (R): 8.75% per annum (floating)
Tenure (n): 20 Years (240 Months)
Monthly EMI: ₹44,186
Total Amount Repaid: ₹1,06,04,524 (Over ₹1.06 Crore!)
Total Interest Burden: ₹56,04,524 (You pay 112% of the loan in interest alone!)
Detailed Year-by-Year Amortization Schedule Table
Year
Annual EMI Paid
Principal Repaid
Interest Repaid
Outstanding Balance at Year End
% of EMI Going to Interest
Year 1
₹5,30,227
₹95,959
₹4,34,268
₹49,04,041
81.9%
Year 2
₹5,30,227
₹1,04,705
₹4,25,522
₹47,99,336
80.3%
Year 3
₹5,30,227
₹1,14,250
₹4,15,977
₹46,85,086
78.5%
Year 4
₹5,30,227
₹1,24,665
₹4,05,562
₹45,60,421
76.5%
Year 5
₹5,30,227
₹1,36,031
₹3,94,196
₹44,24,390
74.3%
Year 7
₹5,30,227
₹1,62,187
₹3,68,040
₹41,12,652
69.4%
Year 10
₹5,30,227
₹2,11,466
₹3,18,761
₹35,27,991
60.1%
Year 13
₹5,30,227
₹2,75,721
₹2,54,506
₹27,65,716
48.0%
Year 15
₹5,30,227
₹3,28,742
₹2,01,485
₹21,37,185
38.0%
Year 18
₹5,30,227
₹4,28,633
₹1,01,594
₹9,93,923
19.2%
Year 20
₹5,30,227
₹5,07,678
₹22,549
₹0
4.3%
Critical Takeaways from the Amortization Data:
The 5-Year Milestone Shock: After 5 full years of religiously paying ₹44,186 every single month (totaling ₹26,51,135 out of pocket), your outstanding principal has only dropped from ₹50 Lakh to ₹44.24 Lakh! Over ₹20.7 Lakhs went straight into the bank's profit ledger.
The Crossover Point: It takes almost 12 to 13 years before more than 50% of your monthly EMI is applied toward principal reduction rather than interest.
The Window of Opportunity: Any extra payment made in Years 1 through 7 has an astronomical compounding impact because it prevents dozens of future compound interest cycles.
5. The 4 Proven Prepayment Strategies (Save ₹15L to ₹30L in Interest)
Prepayment is the legal, mathematical cheat code of debt management. When you make a partial prepayment toward a floating-rate home loan in India, the RBI prohibits banks from charging any prepayment penalties. 100% of your prepayment is deducted directly from the principal loan balance.
Here are the four most powerful prepayment protocols modeled by our financial engineers:
Strategy 1: The "1 Extra EMI Per Year" Protocol
Figure 2: Impact of 1 Extra EMI Payment Per Year
Mechanism: Every year, make one additional EMI payment (13 payments instead of 12). You can time this with your annual company performance bonus, Diwali incentive, or tax refund.
The Numbers on a ₹50L, 20-Year Loan @ 8.75%:
Normal Tenure: 20 Years (240 Months) | Normal Interest: ₹56,04,524
With 1 Extra EMI/Year: Tenure drops from 20 Years to ~16 Years!
Total Interest Saved: ₹11,45,000+
Time Saved: 4 full years of debt freedom!
Strategy 2: The "5% Annual Step-Up EMI" Strategy
Mechanism: As your career progresses, your salary typically rises between 6% and 12% annually. By instructing your bank to increase your monthly EMI by just 5% once every 12 months:
Year 1 EMI: ₹44,186
Year 2 EMI: ₹46,395 (+₹2,209)
Year 3 EMI: ₹48,715 (+₹2,320)
Year 4 EMI: ₹51,151 (+₹2,436)
The Results:
Your 20-year loan is completely eradicated in just 12.5 Years!
Total Interest Saved: ₹22,80,000+ (Saving almost half the total interest!)
Strategy 3: Lump-Sum Prepayment at Strategic Milestones
Mechanism: Making a lump-sum principal repayment of ₹2,00,000 to ₹5,00,000 during the initial 36 months of the loan.
Why Early Timing Matters:
A ₹3,00,000 prepayment made at the end of Year 2 saves approximately ₹9,45,000 in future cumulative interest and cuts tenure by 28 months.
That same ₹3,00,000 prepayment made in Year 15 saves less than ₹1,15,000 in interest because most interest has already been extracted.
Strategy 4: Tenure Reduction vs. EMI Reduction (The Crucial Choice)
Whenever you make a partial prepayment, your bank will present you with two options:
Reduce the Loan Tenure (keep the monthly EMI constant).
Reduce the Monthly EMI (keep the remaining loan tenure constant).
[!IMPORTANT]
Always choose Tenure Reduction. Reducing your tenure keeps your amortization velocity high and maximizes mathematical compounding savings. Reducing your EMI gives immediate monthly budget relief, but results in 40% to 60% lower total interest savings over the life of the loan.
6. Fixed vs. Floating Interest Rates in 2026
When structuring your loan facility, understanding the underlying benchmark rate mechanism is paramount.
External Benchmark Lending Rate (EBLR / RLLR)
Since October 2019, the Reserve Bank of India mandated that all retail floating-rate loans from scheduled commercial banks must be linked to an external benchmark, overwhelmingly the RBI Repo Rate:
Home Loan Rate = RBI Repo Rate + Bank Spread (Margin) + Credit Risk Spread
If the RBI cuts the repo rate by 50 basis points (0.50%), banks are legally required to pass the reduction to borrowers within the reset window (usually within 3 months).
Conversely, when inflationary cycles cause rate hikes, your home loan tenure or EMI expands automatically.
Comparative Framework: Fixed vs. Floating
Feature
Floating Rate Home Loan
Fixed Rate Home Loan
Current Market Range
8.35% – 9.25%
9.80% – 11.50%
RBI Prepayment Penalty
0% (Zero penalty by law)
2% – 3% prepayment penalty often applies
Market Sensitivity
Adjusts automatically with RBI policy
Immune to rate hikes, but misses rate cuts
Suitability
Ideal for 95%+ of Indian home buyers
High-inflation risk aversion or short tenures
7. Tax Deductions on Home Loans in India: Section 24(b) & Section 80C
Smart borrowers leverage tax deductions under the Indian Income Tax Act to effectively slash their net borrowing cost:
1. Interest Deduction: Section 24(b)
Maximum Limit: Up to ₹2,00,000 per financial year on interest paid for a self-occupied property.
Let-out Property: If the property is rented out, the entire interest paid can be set off against rental income, subject to an overall loss cap of ₹2,00,000 across house property heads per year.
Tax Savings Impact: For an individual in the 30% tax bracket (+ cess), claiming the full ₹2,00,000 deduction saves ₹62,400 in direct income tax every year.
2. Principal Repayment: Section 80C
Maximum Limit: Up to ₹1,50,000 per financial year for the principal repayment component, along with stamp duty and registration charges paid in the year of purchase.
Lock-in Period: You cannot transfer or sell the property within 5 years of possession, or the claimed deductions are reversed and taxed as income.
Note: Section 80C is only available if you opt for the Old Tax Regime. Under the New Tax Regime, 80C deductions are not available, though Section 24(b) on let-out properties retains specific provisions.
3. Joint Home Loan Optimization (The Double Deduction Hack)
If you co-sign a home loan with your spouse, parent, or working sibling and both are co-owners of the property:
Both co-borrowers can independently claim up to ₹2,00,000 each under Section 24(b) (Total: ₹4,00,000/year).
Both can claim up to ₹1,50,000 each under Section 80C (Total: ₹3,00,000/year).
Combined annual tax shield = Up to ₹7,00,000 in deductions, saving over ₹2,18,000 in income tax annually!
8. Associated Hidden Costs: What Lenders Do Not Highlight
When budgeting for a loan, the principal and interest are not the only expenses. Always factor in:
Processing Fees: Typically 0.25% to 0.50% of the loan amount + 18% GST (often negotiable or waived during festive promotions).
MODT Charges (Memorandum of Deposit of Title Deeds): 0.1% to 0.5% of loan value depending on state government stamp rules.
Property Valuation & Legal Verification Fees: ₹5,00,000 to ₹15,000 per property dossier.
Loan Protection Insurance: Banks frequently pressure borrowers into single-premium credit protection insurance bundled into the loan. Always compare term life insurance quotes independently rather than buying expensive bundled policies.
9. The Golden Rules of Prudent Borrowing
To ensure your loan enhances your net worth rather than triggering financial distress, apply these institutional risk guidelines:
The 40% FOIR Rule: Your Fixed Obligation to Income Ratio (FOIR)—including your home loan EMI, car loans, and credit cards—should never exceed 40% to 45% of your net monthly take-home salary.
Maintain a 6-Month EMI Contingency Buffer: Keep 6 months of EMI payments in a liquid mutual fund or high-interest sweep account before taking possession, safeguarding you against job loss or medical emergencies.
Review Interest Rates Annually: Check your lender's current spread against competing PSU and private banks. If your rate is more than 0.50% higher than prevailing market rates for your credit tier, request an internal balance conversion (switch fee of ₹1,000–₹5,000) or initiate an external balance transfer.
10. Frequently Asked Questions (FAQ)
Q1. Can I reduce my home loan EMI if the RBI cuts interest rates?
Yes. Under the External Benchmark Lending Rate (EBLR) framework, banks must revise their benchmark floating rates in tandem with RBI repo rate cuts. By default, most lenders adjust your loan tenure downward while keeping your monthly EMI constant. You can explicitly request your bank branch or net banking portal to reduce the EMI instead if monthly cash flow relief is your primary objective.
Q2. Is there any prepayment penalty on home loans in India?
According to binding RBI guidelines, banks, housing finance companies (HFCs), and NBFCs cannot charge any prepayment penalty or foreclosure fee on floating-rate individual home loans, regardless of whether the prepayment is partial or full. However, if the loan is in the name of a business entity or has a fixed interest rate, prepayment charges may apply.
Q3. How does increasing my loan tenure affect my total interest?
Increasing your tenure reduces your monthly EMI, which makes initial loan qualification easier, but massively increases your total interest outflow. For example, taking a ₹40 Lakh loan at 9% for 30 years instead of 20 years reduces your EMI by only ₹5,000/month, but increases your total interest bill by a staggering ₹26,80,000!
Q4. Which is better: paying off a home loan early or investing in mutual funds via SIP?
This depends on your expected post-tax investment return versus your home loan interest rate:
If your home loan interest rate is 8.5% (effective post-tax cost ~6.5% after Section 24b deductions), and long-term equity SIPs historically return 12% to 14% CAGR, investing surplus funds in equity mutual funds generates greater mathematical wealth over 15 to 20 years.
However, for psychological peace of mind and guaranteed risk-free return on capital, eliminating debt early is unbeatable. A hybrid approach—paying 1 extra EMI per year while running a disciplined SIP alongside—delivers the ideal balance.
Q5. Can a high credit score really lower my home loan EMI?
Absolutely. Most major Indian lenders (State Bank of India, HDFC Bank, Bank of Baroda, ICICI) employ risk-based pricing matrices. A borrower with a CIBIL score of 780+ typically receives interest rates 0.40% to 0.75% lower than a borrower with a score of 680. On a ₹50 Lakh, 20-year loan, a 0.50% rate difference translates to savings of over ₹3,50,000 in interest.
Q6. What happens if I miss an EMI payment?
Missing an EMI triggers an immediate late payment penalty (usually 2% per month on the overdue amount), bounces penal charges (₹500+), and is reported to credit bureaus (CIBIL, Experian, Equifax), causing a sharp drop of 40 to 80 points in your credit score. If non-payment extends beyond 90 days, the loan is classified as a Non-Performing Asset (NPA), initiating proceedings under the SARFAESI Act.
Conclusion: Take Control of Your Loan Today
Your home loan does not have to be a 20-year financial burden. By understanding the underlying reducing balance mathematics, monitoring your amortization schedule, and executing structured prepayment protocols like the 1-extra-EMI or 5%-annual-step-up strategy, you can reclaim your financial freedom years ahead of schedule and save tens of lakhs in unnecessary interest.
Put these numbers to work for your own portfolio:
Calculate your exact monthly payments, inspect your customized month-by-month amortization schedule, and experiment with prepayment scenarios using our institutional-grade Personal Loan & Home Loan EMI Calculator.