Education Calculator
College & Career Planning
Education Loan & Amortization Terms
Federal & Private EMI$
%
$
Capitalize In-School Grace Period Interest
Unsubsidized & Private loans accrue interest during the 4 college years ($9.1k added to balance)
Monthly Loan Repayment10-YR FIXED
$501.9
Total Payoff: $60,228 ($25,228 Total Interest)
Post-Grad DTI
10.4%
High (>10% debt strain)
Effective Principal
$44,142
With capitalized grace interest
Institutional Rule of Thumb
Total Student Debt Rule: Never borrow more in total cumulative student loans than your realistic expected starting salary in Year 1 post-graduation. Total borrowing under 100% of starting salary ensures comfortable repayment under a standard 10-year repayment schedule with a debt-to-income ratio under 10%.
College Financing, Inflation & Amortization Schematics
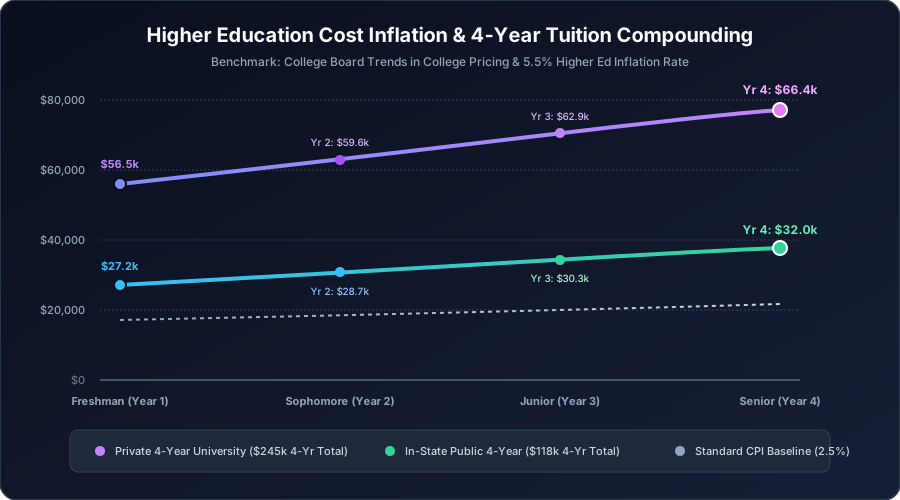
4-Year College Cost Inflation Trajectory
5.5% annual higher-ed compounding vs baseline consumer price index (CPI).
Student Loan Amortization: 10-Yr vs 20-Yr
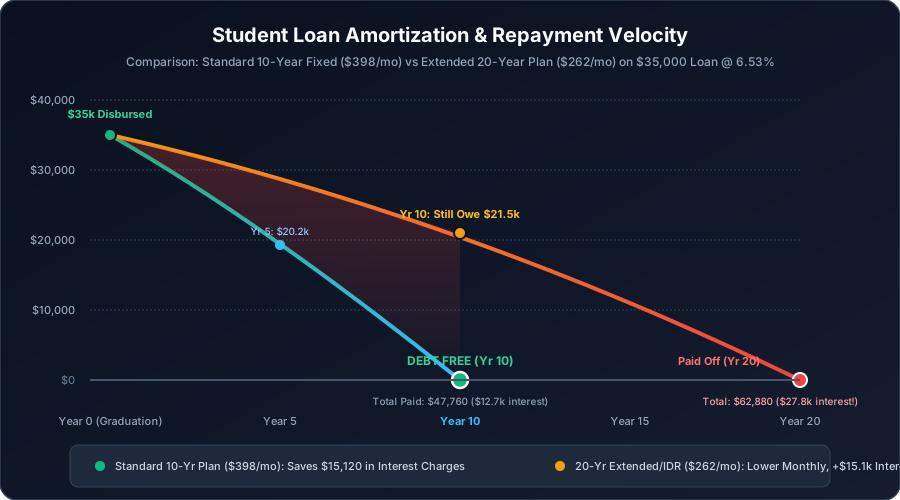
Fast principal reduction vs long-term capitalized interest penalty.
Financial Formulations & Actuarial Modeling
1. Higher-Ed Inflation Compounding
C_total = Σ [C_0 × (1 + r)^y]
Where C_0 is initial freshman budget and r is higher-ed inflation (avg 5.5%).
2. Loan Amortization Equation (EMI)
EMI = P × [i(1+i)^n] / [(1+i)^n - 1]
Where P is principal with capitalized grace interest, i is monthly interest, and n is payments count.
3. 529 SIP Contribution Backsolver
PMT = S_net × [i / ((1+i)^n - 1)]
Solves monthly recurring investment needed to close the remaining gap after factoring compound growth on initial balance.
University Financing Case Studies
Case 1: The 10-Year vs 20-Year Loan Dilemma
Scenario: An engineering graduate with $35,000 debt chooses between standard 10-year ($398/mo) vs extended 20-year ($262/mo). While the 20-year plan frees up $136/mo in immediate cash flow, it costs an extra $15,120 in interest over the life of the loan. Paying off within 10 years yields an effective guaranteed return of 6.53%.
Case 2: Starting a 529 College Plan Early
Scenario: Parents targeting $100,000 for college who start at child age 1 need to contribute $260/month (where $54,000 is earned purely from compound growth). Waiting until age 13 skyrockets the required contribution to $1,380/month due to lost compounding runway.
Frequently Asked Questions
About Student Loan Calculator
Calculate education loan EMI and total interest. Designed for fast, accurate calculation with clear outputs, explanation, and device-friendly usability.
Why this page helps
- Fast answers without manual formula rearrangement
- Cleaner comparison of multiple scenarios
- Works on mobile, tablet, and desktop
- Useful for study, planning, and quick verification
How to use it well
- Open the Student Loan Calculator and enter the known input values.
- Select the correct units for each field before calculating.
- Review the main result, formula, and conversions shown on the page.
- Use the step-by-step breakdown to verify the logic and download or share the result if needed.
Expert tips
- Check that all inputs use the correct unit system before comparing values.
- Use the worked steps to confirm whether you entered the right known variables.